Daily Top 5
Simon refinancing deal shows uneven US mall recovery
Article originally posted in the CoStar on Nov. 5, 2026.
Simon Property Group, the largest U.S. mall landlord, is turning to the commercial mortgage-backed securities market to refinance a group of shopping centers as improving mall performance draws lenders back to the sector.
The Indianapolis-based company is sponsoring or co-sponsoring four loans in the upcoming $805.1 million Benchmark 2026-B44 CMBS transaction. The properties include Colorado Mills near Denver; The Falls in Miami; Arizona Mills in Tempe, Arizona; Pismo Beach Premium Outlets in California; and Queenstown Premium Outlets in Maryland.
The Simon-related loans account for about 20% of the securitization, making Simon its largest related borrower-sponsor, according to Securities and Exchange Commission filings.
The financing provides a snapshot of an uneven mall recovery. Bond-rating firms cite strong sales and active leasing at some of the properties, while flagging falling sales, temporary tenants, upcoming lease expirations and interest-only debt at others. The differences show major malls are again attracting financing, with credit assessments varying considerably by property.
Simon Property did not respond to a request for comment from CoStar News.
Colorado mall rebounds
Colorado Mills offers some of the clearest evidence of recovery.
The 1.1 million-square-foot outlet center in Lakewood, Colorado, would secure a new $93 million mortgage, with $80 million included in the Benchmark securitization. The loan refinances about $84.1 million of previous CMBS debt and returns roughly $5.3 million of equity to its sponsors, according to bond-rating firm KBRA. Simon owns the property with KanAm and the Stevinson family.
Sales have strengthened. Tenants occupying less than 10,000 square feet generated $383 in sales per square foot during the 12 months through July, up from $360 in 2025 and $375 in 2024, KBRA said.
Leasing also has accelerated. From 2024 through 2026, the owners signed or renewed 34 leases covering about 138,000 square feet, or 15% of the property’s leasable area, Fitch Ratings, another bond-rating firm, reported.
The gains have followed substantial investment. The owners have spent about $92 million on capital and tenant improvements since 2016, including $9.2 million during the past two years, according to KBRA.
Arizona charts different course
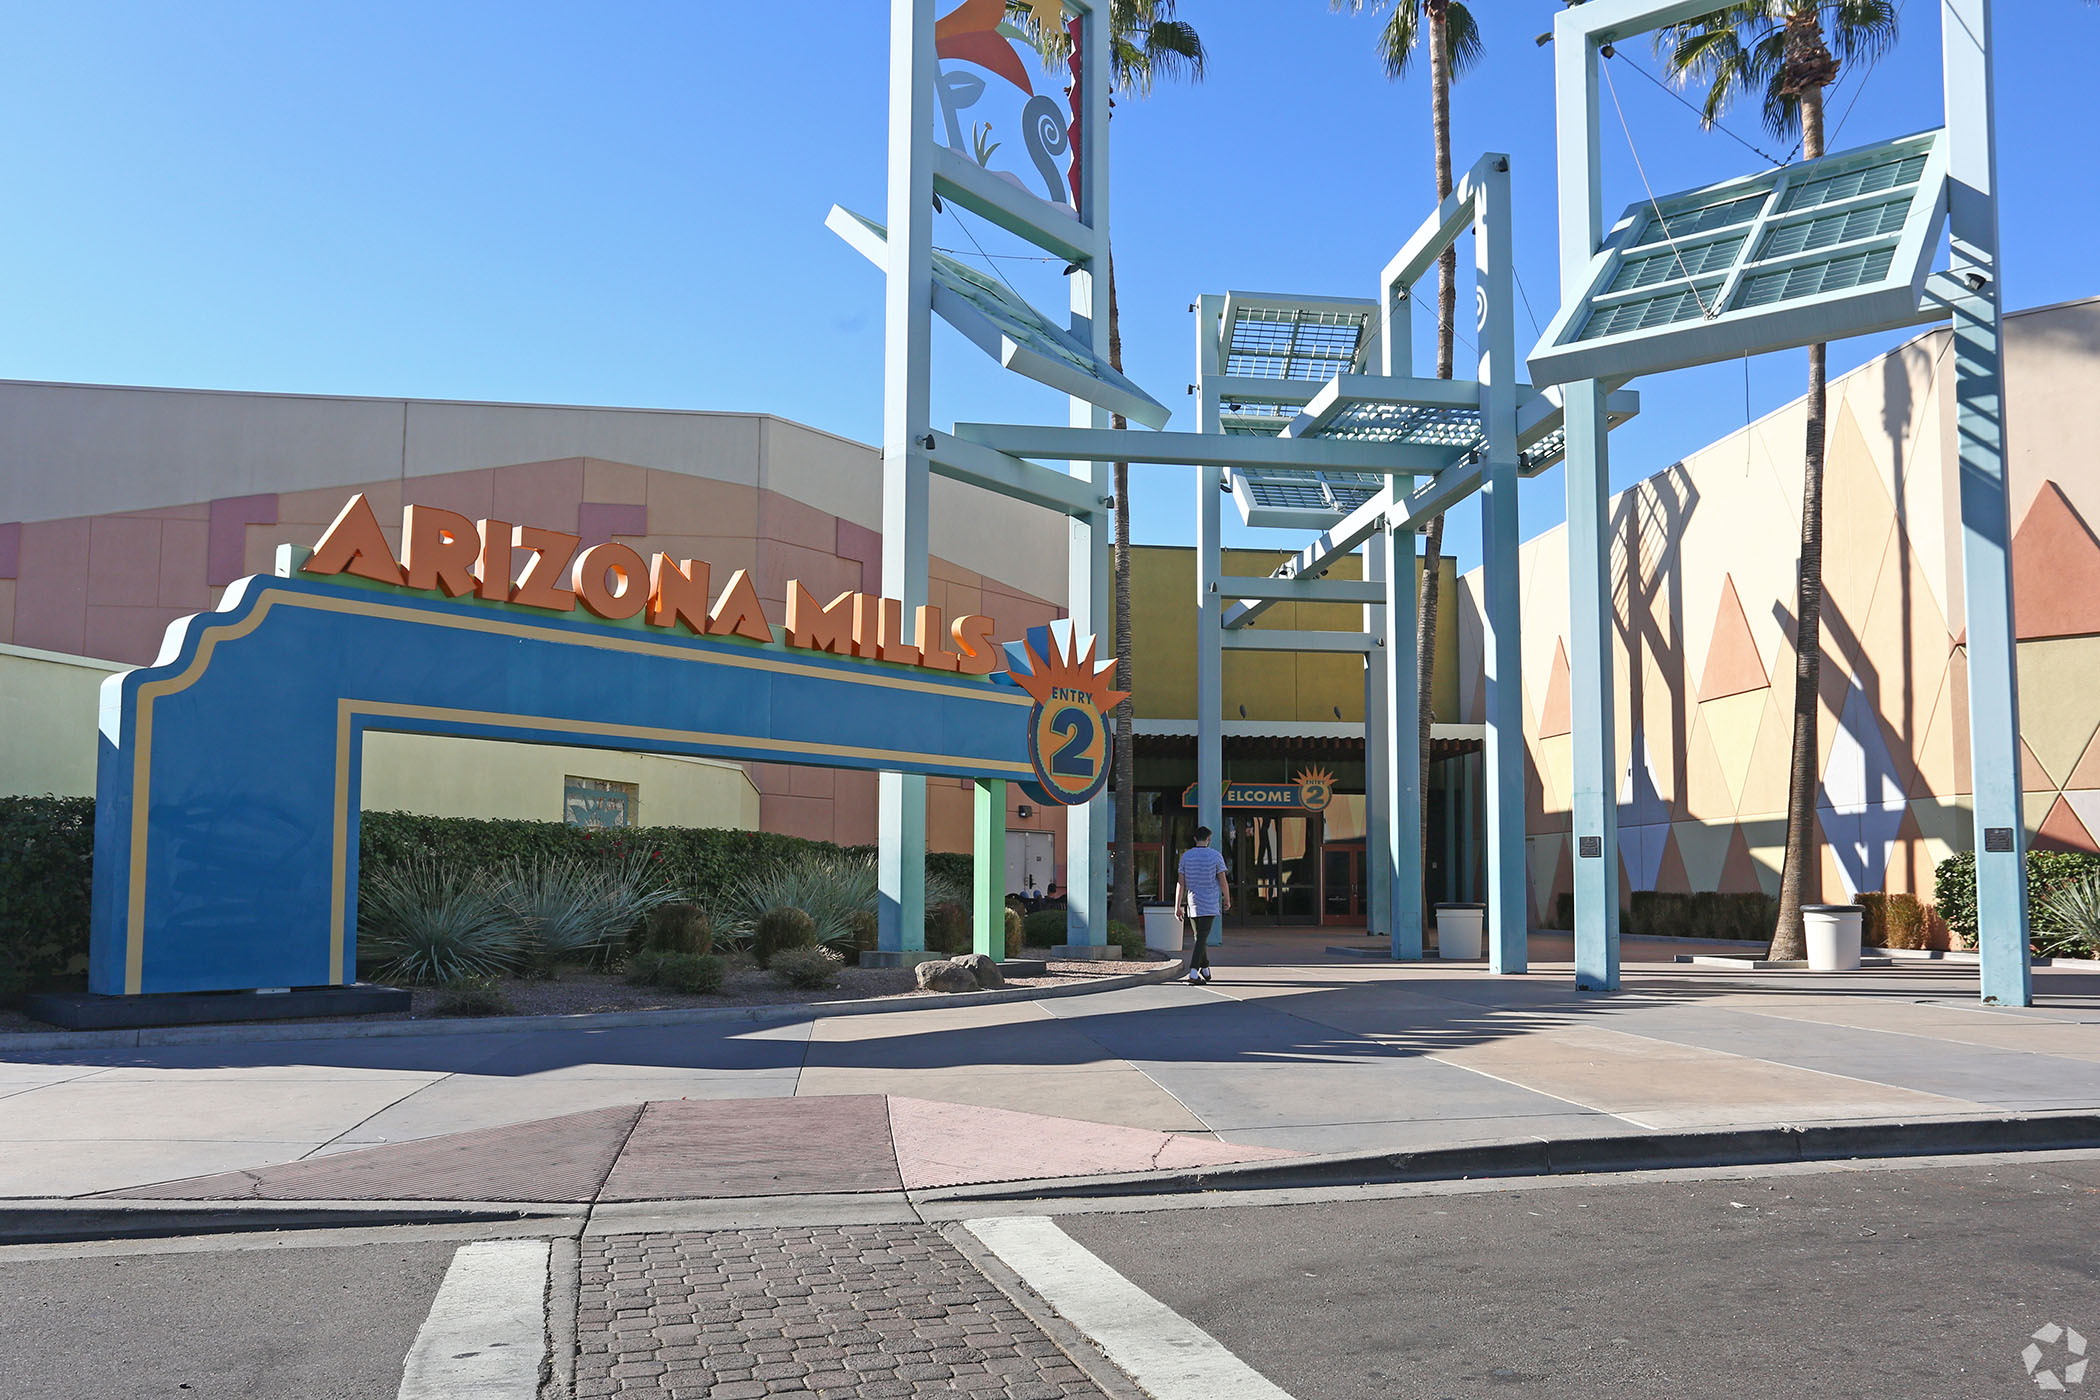
Arizona Mills shows a different trajectory.
The 1.2 million-square-foot enclosed mall in Tempe is securing a $135 million mortgage that repays about $89.4 million of existing CMBS debt, funds reserves and closing costs, and returns about $44.5 million of equity to Simon, according to KBRA.
Arizona Mills has moved in the opposite direction from Colorado Mills. Sales by tenants occupying less than 10,000 square feet declined to $313 per square foot in the 12 months through March from $321 in 2025 and $368 in 2024, KBRA reported.
The property, however, is adding tenants. Arizona Mills combines discount retailers with attractions including Legoland Discovery Center, Sea Life Aquarium, Bubble Planet and a Harkins movie theater with IMAX. Fitch reported that Cavender’s Boot City has leased one of the mall’s larger vacant spaces, while Ulta leased the lower portion of the former Forever 21 and Q space. Foot Locker and Shoe Palace also have expressed interest in additional space, according to Fitch.
The Falls in Miami is another strong-performing property in the financing.
The 711,447-square-foot open-air shopping center, anchored by Life Time Fitness, Macy’s, Regal Cinema and The Fresh Market, posted comparable sales of $587 per square foot among tenants occupying less than 10,000 square feet in the 12 months through February, up from $533 in 2024, according to KBRA.
Total mall sales rose more than 22% to $183.8 million from $150.1 million in 2024. The mall was 93.3% leased in June excluding temporary tenants and 95.6% leased including them.
The Falls is set to secure a $130 million mortgage, with $50 million included in the Benchmark CMBS pool, according to transaction documents.
A fourth Simon-sponsored loan places $5 million of a $75 million mortgage backed by Pismo Beach Premium Outlets and Queenstown Premium Outlets into the securitization. The outlet centers are in Pismo Beach, California, and Queenstown, Maryland.
Mall lending gains ground
The financings come as mall performance nationally continues to improve, according to CoStar analysis. Vacancy is down 30 basis points this year to 7.9% as redevelopment and the filling of former anchor spaces gain traction. Rents have averaged 1.8% annual growth. Mall sales have totaled $4.9 billion this year, putting the market on pace to surpass last year’s $5.2 billion.
Retail properties account for 39% of the $805 million mortgage pool, including 26.7% tied to outlet malls, according to bond-rating firm S&P Global Ratings. Five of the 10 largest loans finance retail properties. The more than $313 million of retail loans is the largest amount for the property type in a conduit deal, which pools mortgages from multiple borrowers into a single CMBS offering, since 2024, according to CoStar analysis of SEC data.
Fitch cited the high mall exposure as a negative because Benchmark’s retail concentration exceeds recent CMBS averages.
Still, Benchmark 2026-B44 shows bond issuers are willing to give investors greater exposure to malls and outlet centers even as credit assessments draw sharper distinctions among individual properties.